
Muskoka residential real estate · Third quarter 2026
Muskoka residential sales fell almost a quarter this summer as prices edged down
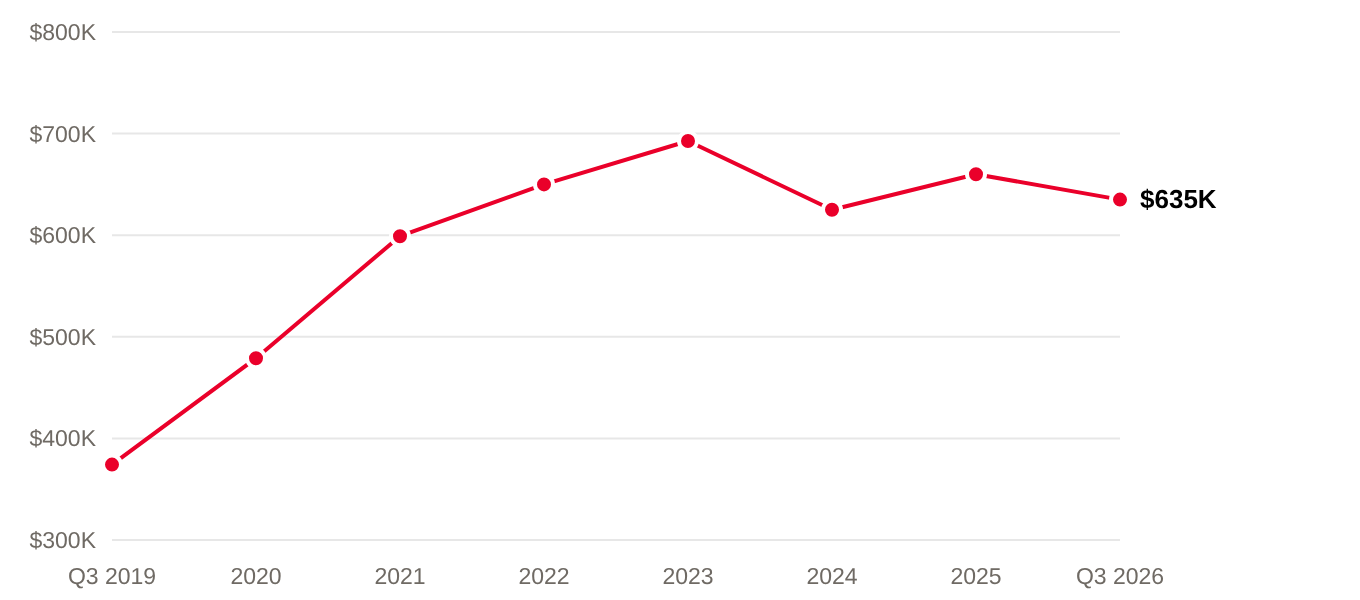
Residential homes sold at a median of $635,000 from July to September, 3.8 per cent below a year ago. Sales fell 23 per cent to 168, and fewer homes sold over the list price.
For the first nine months of the year, residential sales are down 6 per cent (511 to 479).
| Q3 2025 | Q3 2026 | Change | |
|---|---|---|---|
| Sales | 219 | 168 | −23.3% |
| Median sale price | $660,000 | $635,000 | −3.8% |
| Average sale price | $703,639 | $669,358 | −4.9% |
| Lower quartile price | $525,000 | $517,500 | −1.4% |
| Upper quartile price | $827,000 | $780,000 | −5.7% |
| Sold over list price | 10.0% | 7.7% | −2.3 pts |
| Average sale-to-list ratio | 96.6% | 95.8% | −0.8 pts |
| Median days to sell | 30 | 27 | −3 days |
Prices
Median residential sale price, third quarter, 2019 to 2026
Source: OnePoint Association of Realtors.
The median is 8 per cent below its third-quarter high of $692,765 in 2023.
Price ranges
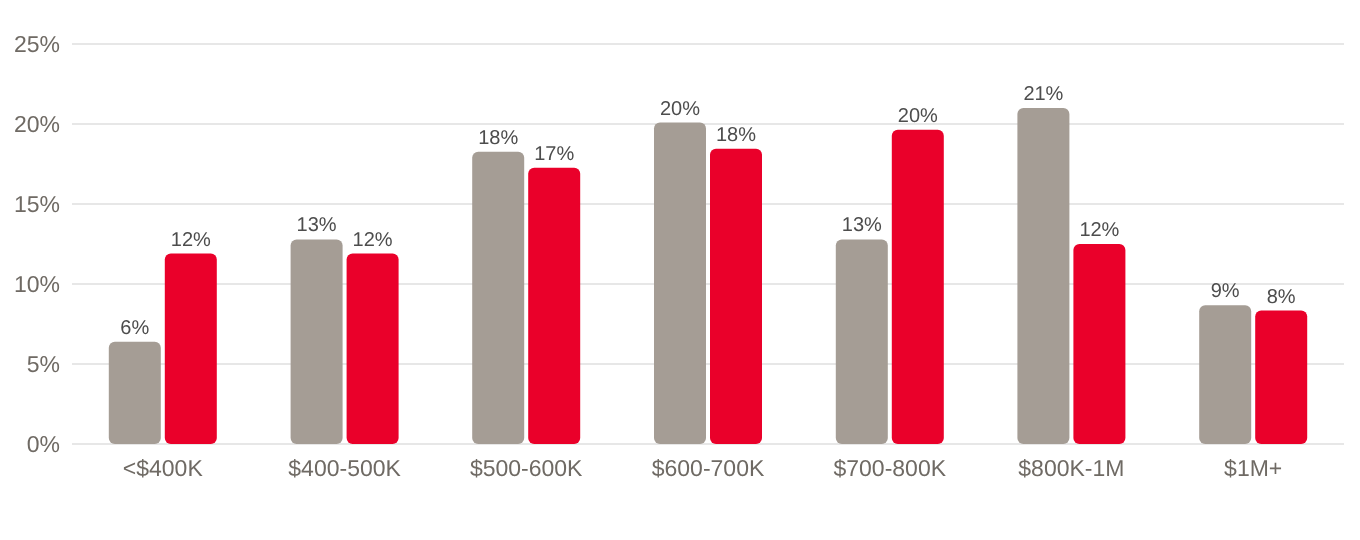
The biggest gain in share was in sales of $700K to $800K (13 per cent of residential sales in 2025 and 20 per cent in 2026). The biggest loss was in sales of $800K to $1M.
Residential sales by price band
Grey is Q3 2025, red is Q3 2026.
Source: OnePoint Association of Realtors.
| Price band | Sales 2025 | Share 2025 | Sales 2026 | Share 2026 | Share change (pts) |
|---|---|---|---|---|---|
| Under $400K | 14 | 6.4% | 20 | 11.9% | +5.5 |
| $400K to $500K | 28 | 12.8% | 20 | 11.9% | −0.9 |
| $500K to $600K | 40 | 18.3% | 29 | 17.3% | −1.0 |
| $600K to $700K | 44 | 20.1% | 31 | 18.5% | −1.6 |
| $700K to $800K | 28 | 12.8% | 33 | 19.6% | +6.9 |
| $800K to $1M | 46 | 21.0% | 21 | 12.5% | −8.5 |
| $1M and up | 19 | 8.7% | 14 | 8.3% | −0.3 |
| All sales | 219 | 100% | 168 | 100% |
Sales Activity
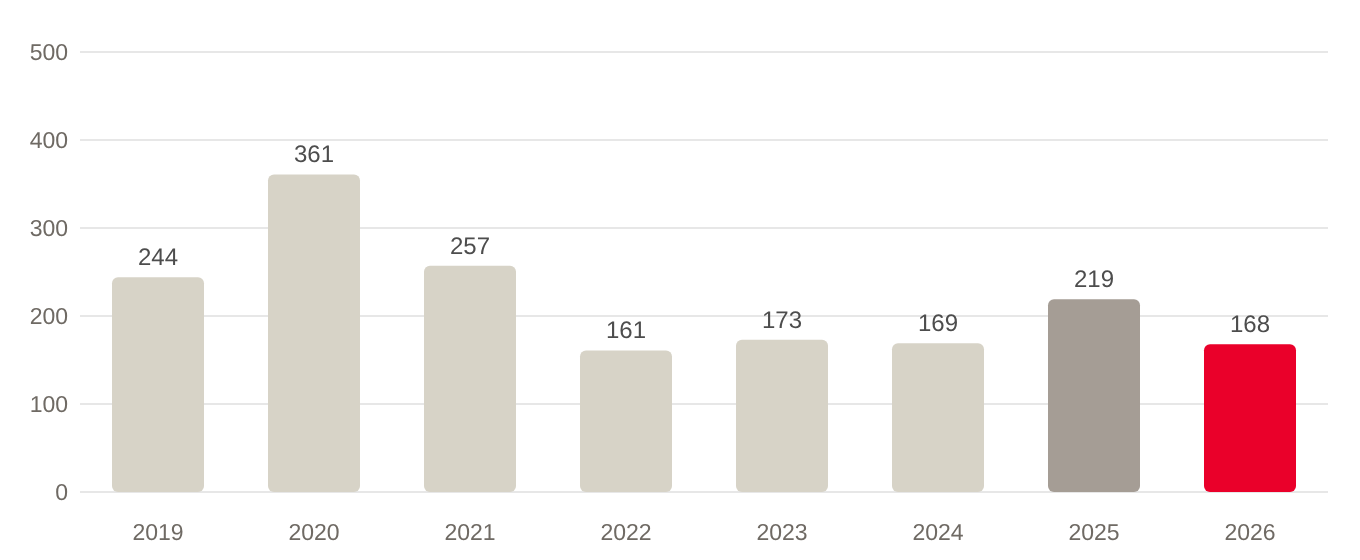
Only 2022 (161 sales) was lower in the past seven third quarters.
Residential single-family sales in the third quarter, 2019 to 2026
Source: OnePoint Association of Realtors.
| Month | 2025 | 2026 | Change |
|---|---|---|---|
| July | 75 | 57 | −24% |
| August | 75 | 59 | −21% |
| September | 69 | 52 | −25% |
Asking prices
These figures use each home's last list price. Many homes were first listed at a higher price and had one or more price reductions or relists before they sold. These figures are measured against the last list price, so the gap between the first asking price and the final sale price is larger than shown here.
Share of sales over list price
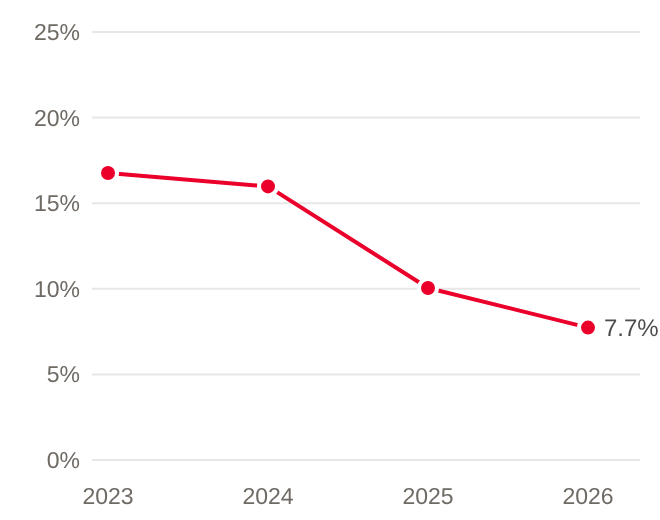
Average sale price as a share of list price
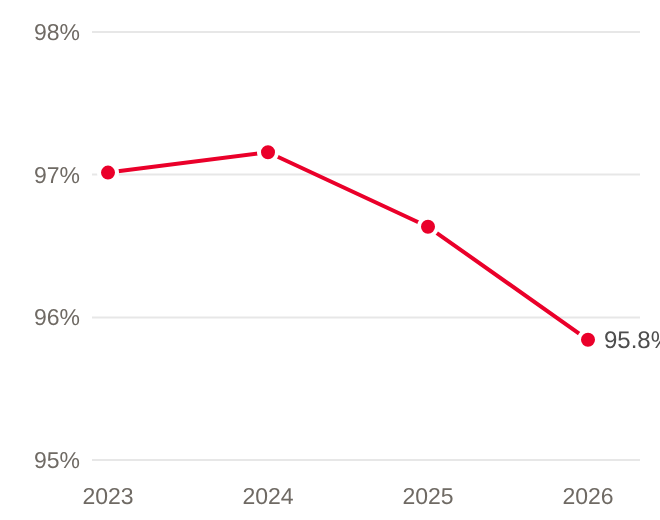
Source: OnePoint Association of Realtors.
| Quarter | Sold over list | Average sale-to-list ratio | Sold 10%+ under list |
|---|---|---|---|
| Q3 2023 | 16.8% | 97.0% | 6.4% |
| Q3 2024 | 16.0% | 97.2% | 5.9% |
| Q3 2025 | 10.0% | 96.6% | 5.0% |
| Q3 2026 | 7.7% | 95.8% | 9.5% |
Inventory and market balance
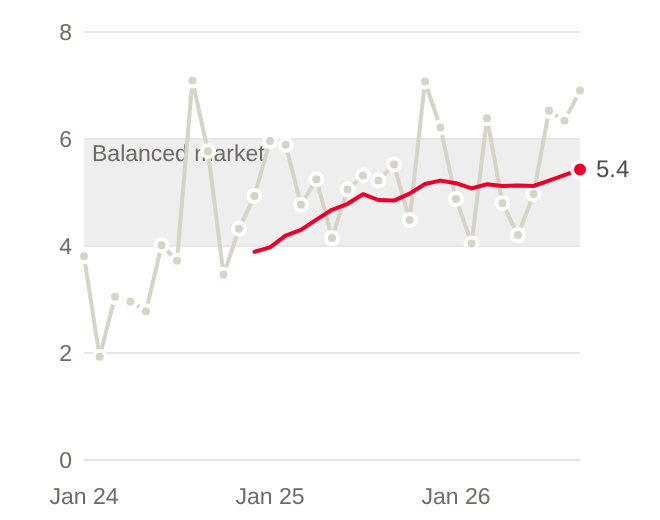
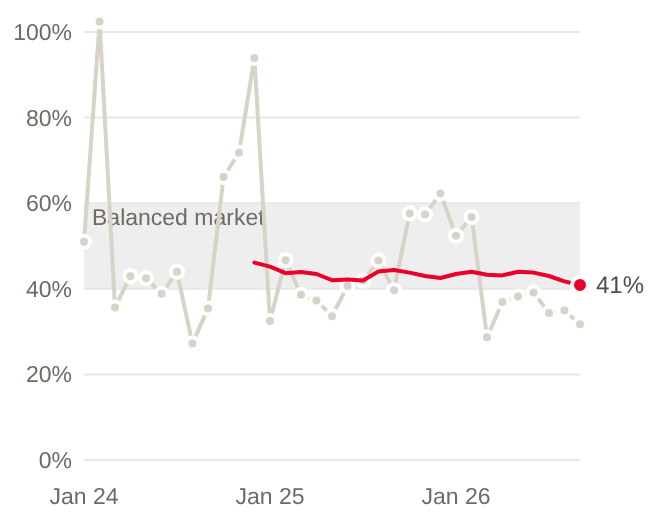
Months of inventory and sales to new listings show whether the market favours buyers or sellers. The rise in months of inventory comes from fewer sales and not necessarily from a larger supply of homes. Months of Inventory over 6 would be generally considered more favourable to buyers. While anything below 40% of sales to new listings would also generally favour buyers.
Months of inventory
Grey is each month. Red is the average of the past 12 months. Shading marks 4 to 6 months.
Sales to new listings
Grey is each month. Red is the average of the past 12 months. Shading marks 40% to 60%.
Source: OnePoint Association of Realtors, Historical Stats report, residential single-family homes in Bracebridge, Gravenhurst, Huntsville, Lake of Bays and Muskoka Lakes, January 2024 to September 2026.
Active listings by month
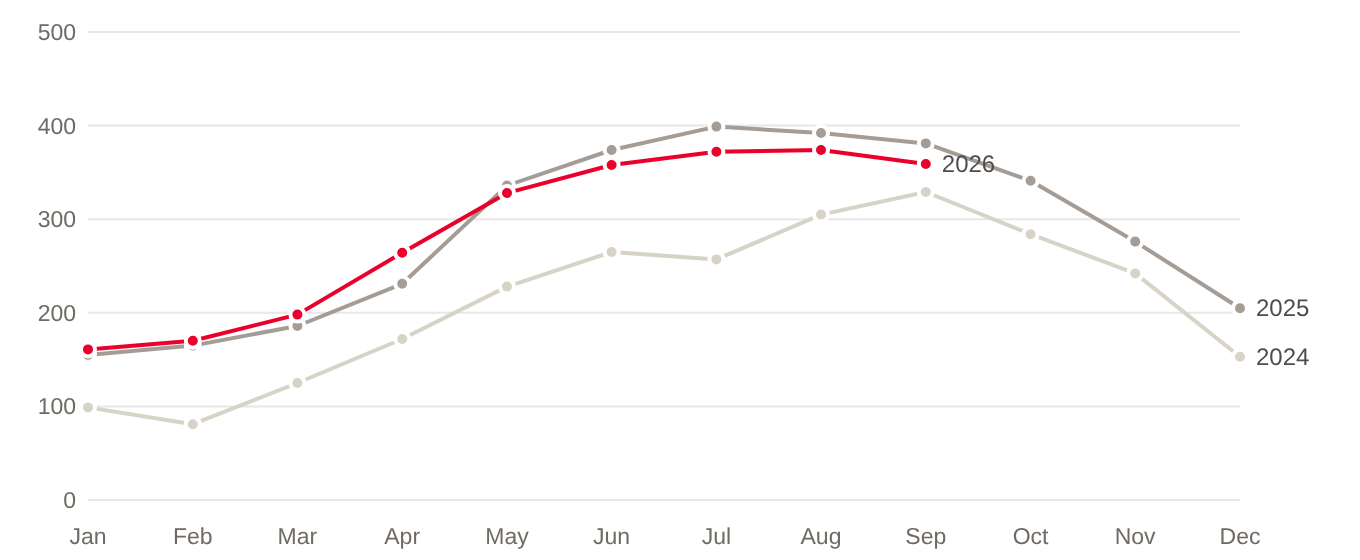
Source: OnePoint Association of Realtors, Historical Stats report, residential single-family homes in Bracebridge, Gravenhurst, Huntsville, Lake of Bays and Muskoka Lakes, January 2024 to September 2026.
Terminations are listings that ended without a sale. Some are relisted, so the count overstates the number of homes that left the market. A higher number still speaks to market in which a higher percentage of homes are not gaining traction ie. showings, offers etc.
| Third quarter (July to September) | 2024 | 2025 | 2026 |
|---|---|---|---|
| Sales | 169 | 219 | 168 |
| New listings | 476 | 514 | 499 |
| Active listings, end of September | 329 | 381 | 359 |
| Months of inventory | 5.3 | 5.4 | 6.6 |
| Sales to new listings | 36% | 43% | 34% |
| Terminations | 65 | 177 | 186 |
| Terminations as share of new listings | 14% | 34% | 37% |
| Average of past 12 months to September: months of inventory | n/a | 4.8 | 5.4 |
| Average of past 12 months to September: sales to new listings | n/a | 44% | 41% |
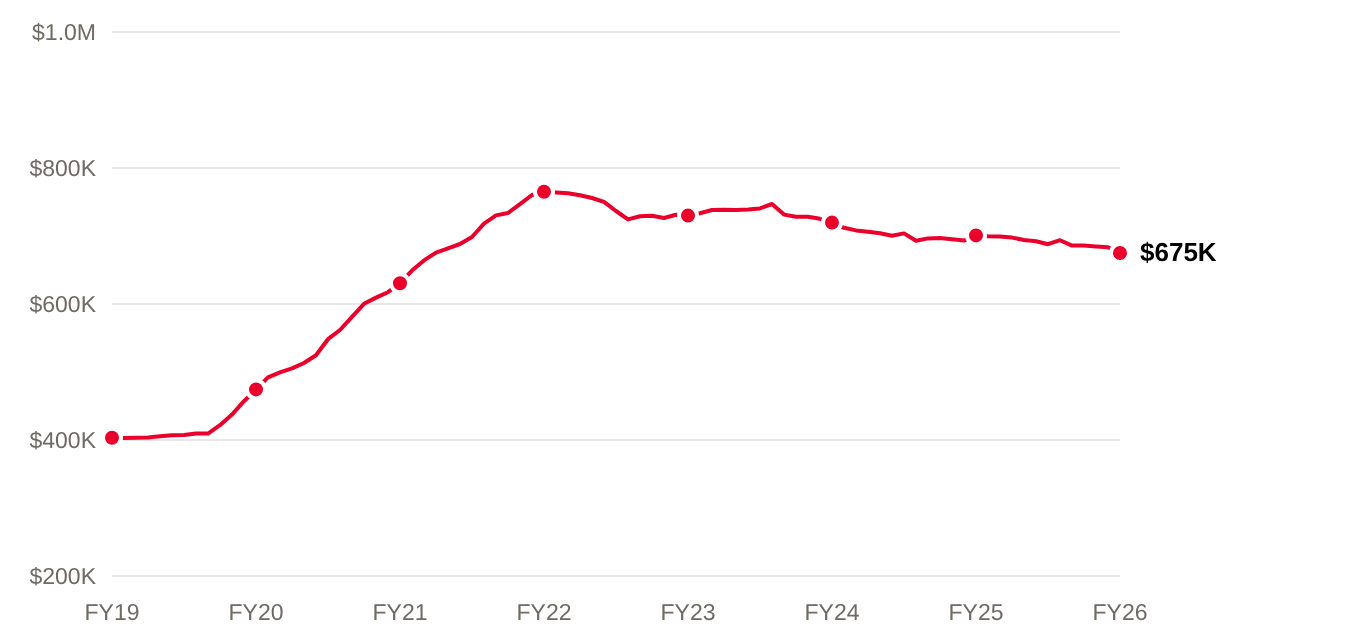
Fiscal-year view: prices over a rolling 12 months
A rolling 12-month window covers every season, so it gives a steadier read than a single quarter. Each point averages all residential sales in the 12 months to that month.
Rolling 12-month average (October to September) residential sale price
Dots mark fiscal year ends.
Source: OnePoint Association of Realtors.
In August 2026 dollars. Dots mark fiscal year ends.
The highest fiscal-year average, since 2019, was $765K in fiscal 2022, and fiscal 2026 is 12 per cent below that.
| Fiscal year (Oct to Sep) | Sales | Median price | Average price |
|---|---|---|---|
| FY2019 | 727 | $376K | $403K |
| FY2020 | 848 | $425K | $474K |
| FY2021 | 1,057 | $588K | $631K |
| FY2022 | 755 | $710K | $765K |
| FY2023 | 597 | $690K | $730K |
| FY2024 | 570 | $660K | $720K |
| FY2025 | 680 | $660K | $701K |
| FY2026 | 627 | $635K | $675K |
| Change, FY2026 vs FY2025 | −7.8% | −3.8% | −3.7% |
Third-quarter history
| Quarter | Sales | Median price |
|---|---|---|
| Q3 2019 | 244 | $374K |
| Q3 2020 | 361 | $479K |
| Q3 2021 | 257 | $599K |
| Q3 2022 | 161 | $650K |
| Q3 2023 | 173 | $693K |
| Q3 2024 | 169 | $625K |
| Q3 2025 | 219 | $660K |
| Q3 2026 | 168 | $635K |
Definitions
- Residential. Single-family homes that are not on the water (non-waterfront).
- Third quarter (Q3). Sales dated July 1 to September 30.
- Median. The middle sale price: half of the homes sold for less and half for more. Lower quartile and upper quartile are the prices below which one quarter and three quarters of homes sold.
- Over list price. A sale that closed above the list price. Sale-to-list ratio is the sale price divided by the list price.
- Days to sell. Days between the list date and the sale date.
- Months of inventory. Active listings divided by the month's sales, or how many months it would take to sell current listings at the current pace of sales.
- Sales to new listings. Sales divided by new listings in the same period. A lower figure means more homes are coming to market than are selling.
- Terminations. Listings that ended without a sale. Some are relisted later.
Notes on the data
- What is counted. Condominiums, townhomes, vacant land, mobile homes and fractional ownership are excluded.
- Source. All sales and listing data are from the OnePoint Association of Realtors.
- Fiscal year. Fiscal years run from October 1 to September 30 and are named for the year in which they end, so fiscal 2026 is October 1, 2025 to September 30, 2026. Rolling figures use all sales in the 12 months ending each month, by sale date.
- List price. The list price in the database is the last list price. It is not the original asking price, and it does not reflect earlier price reductions or relists.
- Area. Only sales labelled Bracebridge, Gravenhurst, Huntsville, Lake of Bays and Muskoka Lakes in the data are included.
- Inventory data. Active listings, new listings, terminations and the sales used for inventory figures come from the OnePoint Association of Realtors Historical Stats report for residential single-family homes in Bracebridge, Gravenhurst, Huntsville, Lake of Bays and Muskoka Lakes, January 2024 to September 2026.
Enjoy this blog post? Click here to subscribe for updates
Leave A Comment